Market overview and structural significance of the Vacuum Gas Oil Market
Our analysis indicates that the Vacuum Gas Oil Market represents a critical intermediate refining stream derived from atmospheric distillation units, serving primarily as elite feedstock for fluid catalytic crackers and hydrocrackers. Valued at $525.77 Billion in 2026, this sector acts as the pivotal bridge between crude distillation and high-value transportation fuels, heavily influenced by sulfur specifications enforced by the International Maritime Organization.
What core drivers, restraints, and opportunities shape the Vacuum Gas Oil Market?
The market is propelled by surging demand for cleaner distillates and tighter environmental regulations from bodies like the EPA. Restraints include high capital expenditures for complex desulfurization units and refining bottlenecks. However, refiners capitalizing on low sulfur vacuum gas oil face lucrative opportunities amidst shifting global bunker fuel specifications.
Emerging trends and transformation patterns across the Vacuum Gas Oil Market
Industry trends highlight an aggressive pivot toward upgrading heavy sour crudes into light products via advanced hydrocracking. Technology innovators like Honeywell International Inc. are deploying proprietary catalyst solutions to maximize conversion efficiency, while regional players increasingly favor low sulfur vacuum gas oil streams to comply with stringent regional environmental mandates.
COVID-19 impact analysis and subsequent recovery trajectory
The pandemic triggered a catastrophic collapse in jet fuel and gasoline demand, severely compressing refinery margins and forcing unplanned distillation run cuts globally. Recovery has been driven by post-lockdown mobility surges, forcing operators like Exxon Mobil Corporation and Shell Plc to optimize their vacuum gas oil yields to capture rebounding middle distillate cracks.
Competitive benchmarking and strategic dynamics in the Vacuum Gas Oil Market
Market concentration is moderately high, dominated by integrated national oil companies and supermajors who leverage captive refining assets. Firms like Saudi Aramco and Kuwait Petroleum Corporation maintain unmatched feedstock security, while merchant refiners like Valero Energy Corporation optimize spot-market trading of high sulfur vacuum gas oil to maximize facility utilization rates.
Executive summary of key findings for the Vacuum Gas Oil Market
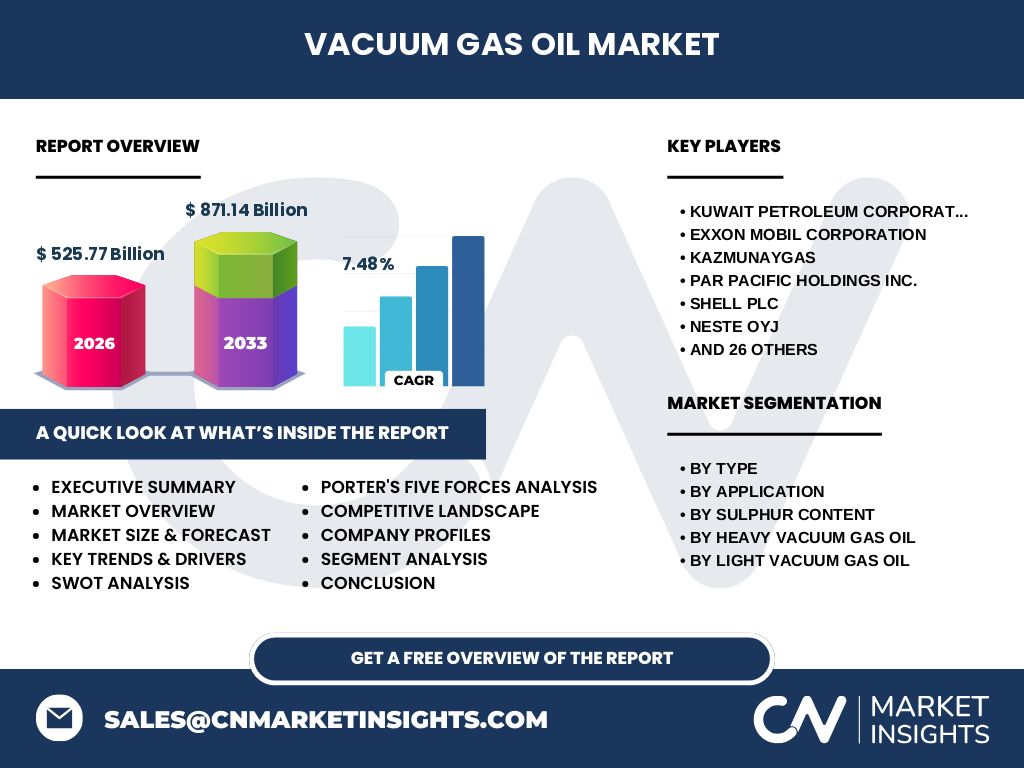
Our comprehensive research underscores a robust trajectory for the sector, projecting market expansion from $525.77 Billion in 2026 to $871.14 Billion by 2033 at a notable CAGR of 7.48%. This growth is underpinned by rising petrochemical integration and escalating global appetite for customized fluid catalytic cracking feedstocks.
Long-term market forecast from 2027 to 2033
The data suggests sustained expansion across the forecast horizon, scaling from the 2026 baseline to reach $871.14 Billion by 2033, expanding at a compound annual growth rate of 7.48%. Accelerated demand for high-conversion hydrocracking feedstock in developing economies will heavily anchor this multi-year valuation leap.
Segmentation analysis across product types, applications, and sulfur grades
Segmentation is categorized by type into heavy vacuum gas oil and light vacuum gas oil; by application covering gasoline production and diesel oil or kerosene production; and by sulfur content into low and high sulfur grades. Heavy variants feed hydrocrackers and fuel oil blending pools, whereas light grades target diesel and naphtha output.
Geographic distribution and regional performance dynamics
Regional performance varies significantly based on local conversion capacities and crude slates. Asia-Pacific dominates consumption driven by massive refining hubs in China and India, whereas North America and Europe focus heavily on upgrading units to process heavier crudes into ultra-low sulfur transportation fuels compliant with strict local environmental standards.
In-depth regional review of high-growth Vacuum Gas Oil Market territories
Asia-Pacific leads volume expansion, spearheaded by mega-refineries like Zhejiang Petroleum and Chemical Co. Ltd. and Reliance Industries Limited. Meanwhile, Middle Eastern producers such as Abu Dhabi National Oil Company and Bahrain Petroleum Company leverage abundant sour crude reserves to export prime vacuum gas oil feedstocks to energy-hungry Asian markets.
Company profiles and strategic positioning of leading industry participants
Key market participants deploy diverse strategies, ranging from integration to specialized blending. Companies like PJSC Lukoil Oil Company, TotalEnergies, and SK Innovation Co. Ltd. focus on proprietary deep-conversion technologies, while regional independents like Par Pacific Holdings Inc. and Axeon Specialty Products optimize niche regional supply chains for asphalt and specialized fuel oil blending.
Porter's Five Forces analysis of the competitive landscape
Bargaining power of suppliers is moderate-to-high, tied directly to crude oil availability and OPEC+ production quotas. Threat of substitutes remains low due to the essential nature of vacuum gas oil as a fluid catalytic cracking intermediate, though intense rivalry exists among merchant refiners vying for optimal spot-market feedstock placement.
SWOT analysis highlighting internal and external market factors
Strengths include established global refining networks and high conversion yields. Weaknesses involve high carbon footprints and vulnerability to crude price volatility. Opportunities lie in low-sulfur hydrocracker feed expansion, while threats stem from accelerating electric vehicle adoption and tightening global decarbonization mandates.
Value chain analysis from upstream extraction to downstream end-users
The value chain initiates with upstream crude extraction, passing through atmospheric distillation to yield atmospheric gas oil before entering vacuum distillation units to produce vacuum gas oil. Midstream traders and refiners then process this intermediate via catalytic cracking or hydrocracking, delivering finished diesel, gasoline, and petrochemical feedstocks to end-users.
Investment insights and high-potential areas for strategic allocation
Our analysis indicates prime investment opportunities reside in hydrotreating and hydrocracking capacity expansions designed to convert high sulfur vacuum gas oil into premium diesel and gasoline blendstocks. Investors should target refiners equipped with deep-conversion units capable of capturing widening spreads between sour crudes and light distillates.
Conclusion and core takeaways for stakeholders
The Vacuum Gas Oil Market represents a resilient, high-value segment within global petroleum refining. With a projected valuation reaching $871.14 Billion by 2033, strategic focus must center on sulfur reduction technologies and integration with petrochemical complexes to capture maximum margin expansion.
Research methodology for baseline estimates and data triangulation
Baseline estimates are meticulously derived by triangulating primary stakeholder interviews with refinery operators, official trade registry statistics, and secondary macroeconomic indicators. Data models reconcile customs export-import flows with national refining throughput data to establish accurate market sizing for 2026 and subsequent forecasts.
Scope of the report and analytical boundaries
This report encompasses global demand, pricing dynamics, and capacity trends for vacuum gas oil across major refining regions. Limitations exclude upstream exploration economics and downstream petrochemical derivative pricing beyond immediate cracking outputs, focusing strictly on primary intermediate refining streams.
Recent developments, capacity additions, and strategic partnerships
Recent industry momentum features major capacity expansions by operators such as Indian Oil Corp. Ltd. and PTT Public Company Limited, alongside strategic processing agreements. Refiners are increasingly investing in proprietary hydroprocessing catalysts to process heavier feedstocks while meeting stringent regional sulfur emissions regulations.